

JPay
by Jpay Mobile
3.9
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 3.9
- Price
- Free
- Download
- 5.00M
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
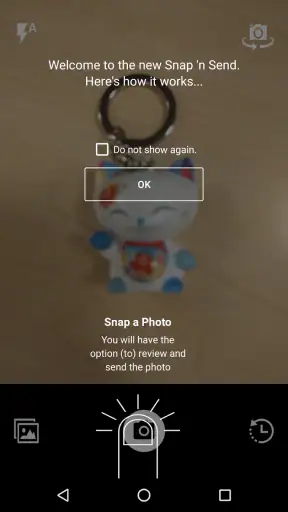
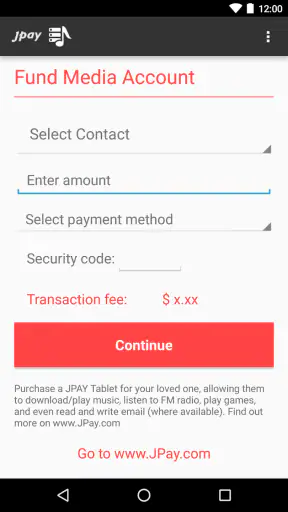
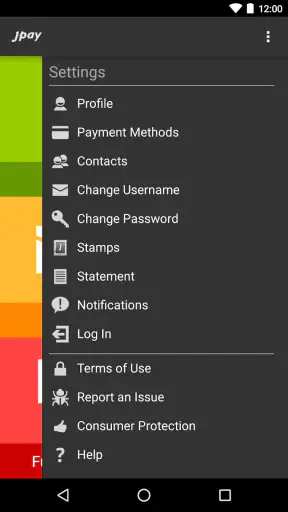
 Analysis by Getfullapps
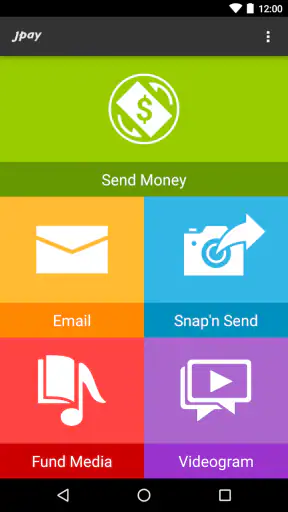
I approached JPay as a practical finance app rather than as a general messaging tool. Its main purpose is to help people send money and exchange emails and photos with someone who may be difficult to reach through ordinary banking or communication services. That makes it a very specific product, and the right question is not whether it can replace every financial app on a phone. The better question is whether its particular combination of payments and communication fits your situation.
In my experience, the app makes the most sense in households that need to coordinate support for a person who is away from home or connected through the JPay system. A relative might need to arrange money, send a message, and share a photo without switching between several unrelated services. That combined workflow is the strongest reason to consider it. If you only need everyday transfers between friends, a conventional banking app may feel more familiar and flexible.
How JPay fits into shared household use
I’d use this section to think through how a household can coordinate around JPay without turning one person’s account into a shared family login. Agreeing on who checks recipient details, who handles messages, and how everyone records contributions can make the routine clearer while keeping financial decisions accountable.
A realistic family scenario
Imagine a household where one person handles most financial tasks while another family member is responsible for staying in touch. A parent may want to send funds, while a sibling wants to write an email and attach a family photo. With JPay, those activities sit in the same app, so the household can coordinate around one account or one shared purpose instead of passing screenshots between different services.
That does not mean everyone should automatically use the same login. I would treat the app as a personal finance and communication tool, even when several relatives are involved. Decide in advance who is responsible for checking the recipient, reviewing the amount, and keeping track of messages. Shared phones make this especially important because an open session can expose conversations or allow an unintended action by the next person who picks up the device.
The useful household habit is simple: one person prepares the transaction, another person verifies the recipient and amount when the transfer is important, and the family keeps its own note of what was sent and why. That small separation helps avoid confusion when several relatives contribute money during the same week. It also prevents the app from becoming the only place where the family remembers its financial commitments.
Keeping account boundaries clear
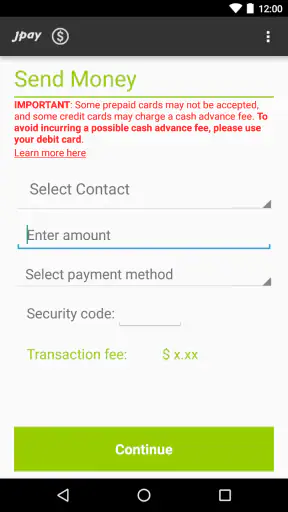
JPay is free to install, but that should not be confused with every possible action inside a financial service being cost-free. Before sending money, I would review the final confirmation screen carefully and make sure the payment destination is correct. A free app can still connect you to transactions where the important consideration is the amount being sent, not the download price.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
I also recommend using separate device profiles or signing out when a phone is shared. The app combines sensitive communication with financial activity, so leaving it open is more consequential than leaving a weather app or a casual game running. If two adults in a household use the same device, they should agree on whose account is active before opening the app and avoid saving personal details in places another user can accidentally access.
For families supporting someone over a long period, a basic record outside the app is worthwhile. Write down the date spoken aloud in ordinary terms, the purpose of the transfer, and which relative made it. I would not rely on memory or on scrolling through old messages to reconstruct household spending. This is one of the less obvious trade-offs: the integrated design makes individual tasks convenient, but it does not replace a family’s own bookkeeping system.
Coordinating money, emails, and photos
The app’s combination of money transfers, email, and photo exchange can reduce the number of steps in a support routine. I can see the appeal of writing a short message before sending funds, or following a financial action with a family photo that gives the recipient a sense of connection. Those actions are related, but they should still be treated as separate decisions. A warm message does not substitute for checking payment details, and a successful transfer does not prove that an email or photo was received in the way you intended.
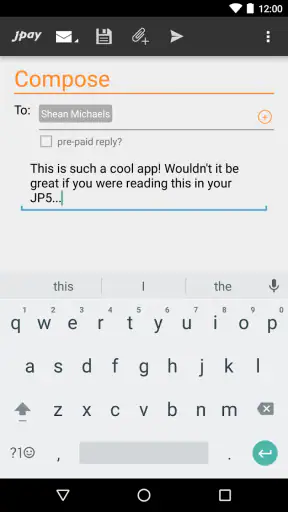
My preferred workflow is to prepare the communication first, reread it, and then handle the money separately. For a recurring family task, use a consistent subject or opening line so relatives can quickly understand the purpose of a message. Keep the financial explanation factual and avoid placing account numbers, passwords, or other highly sensitive information in an email or photo caption. This is especially useful when several family members are helping and need to understand the context without receiving unnecessary private details.
Photos have a different role from payments. They can make communication feel personal, but I would choose images carefully when other relatives share the same phone or when a device is likely to be viewed by someone else. A household should agree on which pictures are appropriate to send and who is allowed to select them. That may sound obvious, yet combining photos with financial communication increases the chance that someone treats the app like a casual social messenger when it deserves more care.
What the age rating means in a household
The app carries a Teen content rating, but I would not interpret that as a recommendation for unsupervised financial use by younger users. Sending money is an adult responsibility in most households, and the person operating the account should understand the recipient, the amount, and the consequences of confirming an action. A teenager might help draft an email or choose a photo, while an adult reviews and completes the financial step.
This arrangement is not about inventing controls the app may not have. It is simply a household boundary. If a young person uses a shared device, I would keep the financial portion with the adult who owns the account and explain why the app is being used. That creates trust without pretending that an age label handles supervision for you.
The same principle applies to older relatives who may be less comfortable with mobile finance. I found that a short written routine is more useful than assuming everyone will remember the process: open the correct account, confirm the intended recipient, check the amount, review the message separately, and close the session. The app can support coordination, but the family still has to provide the judgment.
Setup: what I would decide before using it
JPay was released on October 15, 2012, and the current version is 26.4.0. It supports devices running operating system 11 or later, so I would check the phone before planning a household workflow around it. This matters when a family uses an older spare phone for shared tasks. If that device cannot run the current app, moving the account to a newer phone may be necessary before anyone can rely on it.
During setup, I would use the account belonging to the person who will actually manage the transactions, not a casually shared household email. Keep the login details private, and decide how the family will communicate about a transfer without handing the account to every contributor. If one relative funds the account and another handles messages, those roles should be agreed upon outside the app.
I would also test the communication workflow before making it part of an urgent routine. Send a low-stakes message, confirm that the intended person can access it, and learn where the app presents the status of an action. Do the same mentally with a transfer: identify the recipient, verify the amount, and make sure everyone knows who is responsible for the final confirmation. Testing the process early is more valuable than discovering a confusion when a family member needs help quickly.
Where the app is genuinely convenient
The biggest strength is focus. JPay is built around a relationship between financial support and direct communication, rather than trying to be a complete bank, social network, and photo library at once. For the right user, that narrower purpose is helpful. I do not have to compose a message in one service, search for a payment option in another, and then explain to relatives which transaction belongs to which conversation.
It is also useful when the recipient and sender need more than a bare transfer. A payment without context can leave relatives wondering whether the right amount arrived or what it was intended to cover. Pairing a concise explanation with the transaction can make the household’s support more organized. I would still retain independent records, but the shared context is a practical advantage.
The app has attracted a substantial audience, with over five million installs, around one hundred four thousand ratings, and an average rating of 3.9. Those figures suggest that it is established enough to have been tried by many people, while the rating also reminds me not to present it as universally smooth. A large user base is reassuring when choosing a specialized tool, but it does not remove the need to check whether it fits the specific recipient and institution involved.
Friction I would want users to expect
The narrow focus that makes JPay useful can also make it a poor substitute for a normal bank app. I would not choose it as my only finance application for budgeting, managing everyday bills, or moving money among friends unless my needs specifically matched its supported communication and payment environment. People looking for broad account management may be better served by their bank’s app or a mainstream payment service.
There is also a mental burden in combining personal messages with financial actions. A busy user may move quickly because the email feels informal, then treat the payment with the same casual speed. I think that is the wrong rhythm. Slow down for the money step, even if the message takes only a minute. This is an important trade-off: convenience comes from bringing tasks together, but the design can encourage users to underestimate the seriousness of one of those tasks.
Shared-device use creates another weakness that is not obvious from a short store summary. The app may be convenient for a household, but convenience can become exposure when several people use one phone. I would avoid leaving the account open, avoid handing the device around during an active transaction, and keep family discussions about payment responsibility outside the message thread when possible. A shared device needs shared discipline.
How it compares with ordinary alternatives
Compared with a bank application, JPay is more specialized and more communication-oriented. A bank app is usually the natural choice when I need a broad view of accounts, routine transfers, and standard financial management. JPay becomes more compelling when the payment is part of an ongoing communication relationship and the recipient is supported through the service’s particular network.
Compared with a general messaging app, JPay has a more practical financial purpose. A messaging service may be better for group conversations, casual photo sharing, and everyday family chat. JPay is the more relevant option when the household needs to connect communication with sending money. I would not force it to replace a family group chat; I would use the tool that matches the task.
Compared with a peer-to-peer payment service, the choice depends on the recipient and the reason for sending. Mainstream payment apps are often more natural for friends, roommates, and local household expenses. JPay is better suited to its specific support scenario. The mistake would be choosing it because it combines several features, without first checking whether the person receiving the support can actually use that channel.
Privacy, trust, and practical habits
Trust matters more here than convenience alone. Before sending anything, I would verify the recipient through a known family contact rather than relying on a name that merely looks familiar in the app. If several people share similar names, a second check is sensible. I would also ask contributors to confirm the amount in a private household channel before the person operating JPay completes the transaction.
For communication, keep messages clear and restrained. A short note explaining the purpose of support is easier to review later than a long conversation mixed with unrelated family updates. If a photo includes other people, I would ask whether they are comfortable with it being sent. These habits are not special features; they are the practical safeguards that make a specialized app safer to use in a real family routine.
Another useful boundary is separating urgency from emotion. If a message creates pressure to send money immediately, pause and verify the request through a second route. The fact that JPay handles email and payments in one place should make coordination easier, not eliminate independent confirmation. Families are especially vulnerable to misunderstandings when one person is worried and another is acting quickly.
Who should use it and who should skip it
I would recommend JPay to adults who need a focused way to send financial support while staying in contact with a recipient through emails and photos. It is particularly suitable for a household with clearly assigned responsibilities, a compatible phone, and a recipient who is part of the service’s intended ecosystem. The app’s free availability also makes trying the communication workflow straightforward before committing to a regular routine.
I would skip it if I only needed ordinary banking, broad budgeting tools, or casual payments among friends. I would also avoid making it the center of a shared-device setup when the family cannot agree on account ownership and transaction responsibility. In those cases, a bank app for money and a separate messaging service for conversation may create clearer boundaries, even if that means using two apps.
My household verdict
JPay is a specialized finance app with a human purpose: helping people send money while maintaining a direct line of communication. I like the way it brings those related tasks together, and I can see why a family supporting someone from a distance would value that arrangement. The strongest experience comes from treating it as a focused tool, not as a replacement for every financial or social app already on the phone.
For a household, my recommendation is to establish the boundaries first: one accountable adult for transactions, private login handling, a second check for important payments, and a separate family record. Let younger relatives contribute to messages or photos only within the limits the adults set. With those habits, the app can make a recurring support routine less fragmented.
My final view is positive but specific. JPay is worth considering when its payment-and-communication combination matches your recipient and your family’s needs. It is not the best general-purpose finance choice, and its convenience requires careful handling on shared devices. If you understand that trade-off, use a compatible operating system, and keep account responsibilities clear, it can be a useful part of a household communication routine.
Pros
- Convenient mobile access to send money and support to incarcerated loved ones.
- Transaction history makes it easier to track payments and previous activity.
- Supports communication features in addition to financial services in one app.
- Available on both Android and iOS for broader device compatibility.
- Useful notifications can help users monitor account and transaction updates.
Cons
- Service availability and features vary by correctional facility.
- Fees can make frequent payments and messaging relatively expensive.
- Transfers may be delayed by facility approval and processing times.
- Account setup may require detailed inmate and facility information.
- App usefulness is limited if the recipient’s facility does not use JPay.
FAQs for JPay
What is JPay used for?
JPay is a service designed to help people communicate with incarcerated individuals and manage certain correctional-facility-related services online or through its mobile app. Depending on the facility, users may be able to send electronic messages, add photographs, send money, purchase stamps, schedule video visits, or access other available services. Features vary significantly by state, agency, and institution.
Can I use JPay to send messages and photos?
In many participating facilities, JPay allows users to exchange electronic messages with an incarcerated person, sometimes including approved photographs or attachments. Messages are not private in the same way as ordinary email because they may be reviewed, delayed, rejected, or removed by facility staff. Availability, attachment rules, message limits, and stamp requirements depend on the correctional institution and local policies.
How do payments and money transfers work in JPay?
JPay may allow users to purchase messaging stamps, fund an incarcerated person’s account, or send money for approved purposes using a supported payment method. Before confirming a transaction, review the total amount carefully because service fees, processing charges, minimums, and transfer limits can apply. Processing times and refund policies may also vary according to the facility and payment type.
Is JPay available at every correctional facility?
No. JPay’s services are not universal, and the features offered can differ from one correctional facility or jurisdiction to another. Some institutions may support messaging and payments but not video visitation, while others may use a different provider entirely. It is important to search for the incarcerated person and verify the facility before downloading the app or making a payment.
Is JPay safe and what should I know before using it?
JPay uses account access controls and payment-security measures, but users should still protect their login details, use a strong unique password, and avoid sharing verification information. All communication and transactions may be subject to facility rules, monitoring, and approval. Check recipient details before sending money or messages, keep confirmation records, and contact official JPay support if a transaction or account issue occurs.

JPay
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via JPayAndroidConsumerFeedback@aventiv.com, visit https://www.jpay.com, or review their https://www.aventiv.com/privacy/.










